When you’re just starting out, it’s tempting to run everything through your personal checking account. It’s simple, it’s what you already have and your business may be small enough that it doesn’t seem to matter. But keeping business and personal money separate is one of the simplest and most important habits a business owner can build. It makes bookkeeping easier, simplifies taxes, protects you legally and helps you understand how your business is really doing.
Why separation matters
Cleaner bookkeeping is the most immediate benefit. When business and personal transactions are mixed together, figuring out what your business actually earns and spends becomes a time-consuming puzzle. With separate accounts, every transaction in your business account relates to the business, giving you a clear picture of revenue, expenses and profitability.
Easier taxes follow naturally. Business expenses may be deductible, reducing your taxable income, but you need to track and support them. Separate accounts make it much easier to identify deductible expenses and provide documentation if you’re ever audited. Mixing funds can make it harder to prove which expenses were legitimately for business.
Liability protection matters for owners of LLCs and corporations. These structures can help shield your personal assets from business debts and lawsuits. But if you mix personal and business funds, treating the business as an extension of yourself, it can become easier for a court to disregard the separation and hold you personally responsible. This is sometimes called piercing the corporate veil. Keeping finances separate helps preserve the liability protection these structures are designed to provide.
A professional image is another benefit. Paying vendors and receiving payments through a business account looks more professional to clients, suppliers and lenders. Lenders reviewing a loan application will also want to see clear business financial records.
How to separate your finances
Open a business checking account. Many banks and credit unions offer accounts designed for small businesses, some with no monthly fees. You’ll typically need your EIN if you have one, your business formation documents if you’ve formed an LLC or corporation and any business licenses or DBA registration. Sole proprietors without an EIN can often open an account using their Social Security number.
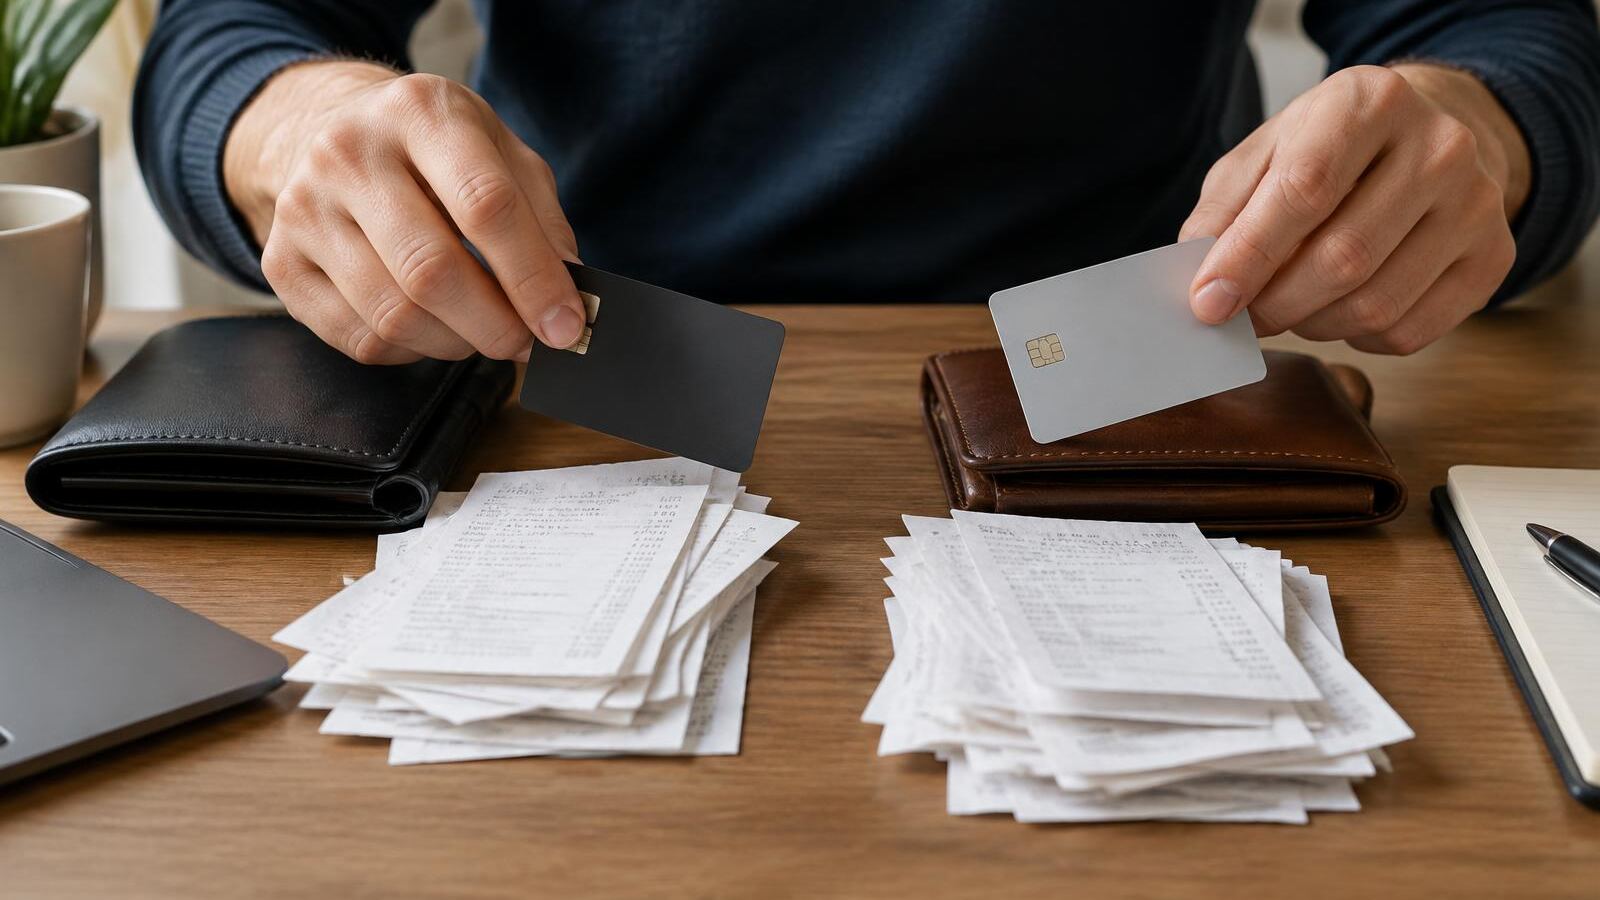
Get a separate card for business purchases only. A business credit card or debit card linked to your business account makes it easy to track expenses. Some business credit cards offer rewards on common business purchases. If you use a credit card, pay it off in full each month to avoid interest.
Deposit all business income into the business account, including payments from customers, platforms and payment processors. Avoid depositing business income into personal accounts.
Pay business expenses only from business accounts. If you accidentally pay for a business expense personally, or vice versa, record it and reimburse the appropriate account so your records stay accurate.
Use bookkeeping software or a spreadsheet to track everything. Many bookkeeping tools can connect to your business bank account and categorize transactions automatically, making it easier to monitor your finances and prepare for taxes.
Paying yourself
Instead of spending directly from the business account for personal expenses, move money to your personal account on a regular schedule, such as twice a month. This creates a clear line between business and personal finances and helps you budget personally with a more predictable income.
How you pay yourself depends on your business structure. Sole proprietors and owners of single-member LLCs taxed as sole proprietorships typically take owner’s draws, transferring profits from the business to themselves. Partners in partnerships and multi-member LLCs also generally take draws. Owners of corporations, including S corporations, who work in the business generally pay themselves salaries through payroll, with taxes withheld, and may also take distributions. S corporation owners must pay themselves reasonable compensation for the work they do.
An accountant can explain what fits your setup and help you plan for taxes.
Keep good records
Save receipts, invoices, bank statements and other financial documents. For each expense, note the business purpose, especially for expenses like meals, travel and equipment. Digital tools make it easy to photograph and store receipts.
Good records make tax time much less stressful, help you understand your business’s performance and protect you if the IRS has questions. The IRS generally recommends keeping records for at least three years after filing, and longer in some situations.
Set aside money for taxes
When you’re self-employed or run a business, no one withholds taxes for you. You’re responsible for paying income tax and, for many business owners, self-employment tax. Many business owners make quarterly estimated tax payments to avoid penalties.
Move a portion of each payment into a separate savings account for taxes, so the money is there when your tax bill arrives. The right percentage depends on your income, deductions and tax situation, so a tax professional can help you estimate how much to set aside.
Start now, even if you’re small
Separating your finances is easiest when your business is just starting. Building these habits early sets a strong foundation that will serve you well as your business grows.
Content on The Evergreen Edit is for educational and informational purposes only and is not individualized financial, investment, tax or legal advice. Learn more.
This article is for educational purposes only and isn't personalized financial, tax or legal advice. Consider talking with a qualified professional about your situation.

Kiara Miller — Founder & Editor
Kiara Miller is the founder and editor of The Evergreen Edit. He has been doing independent finance research for two decades and reviews every article before it's published.
More about Kiara →Get smarter about your money.
Join readers who get The Sunday Edit every week.