Prenuptial agreements have a reputation for being unromantic, sometimes seen as a sign that a couple expects their marriage to fail. But many couples see them differently, as a practical way to set clear expectations, protect assets and have honest conversations about money before marriage. Prenups have become more common, including among younger couples and those without significant wealth.
What a prenuptial agreement does
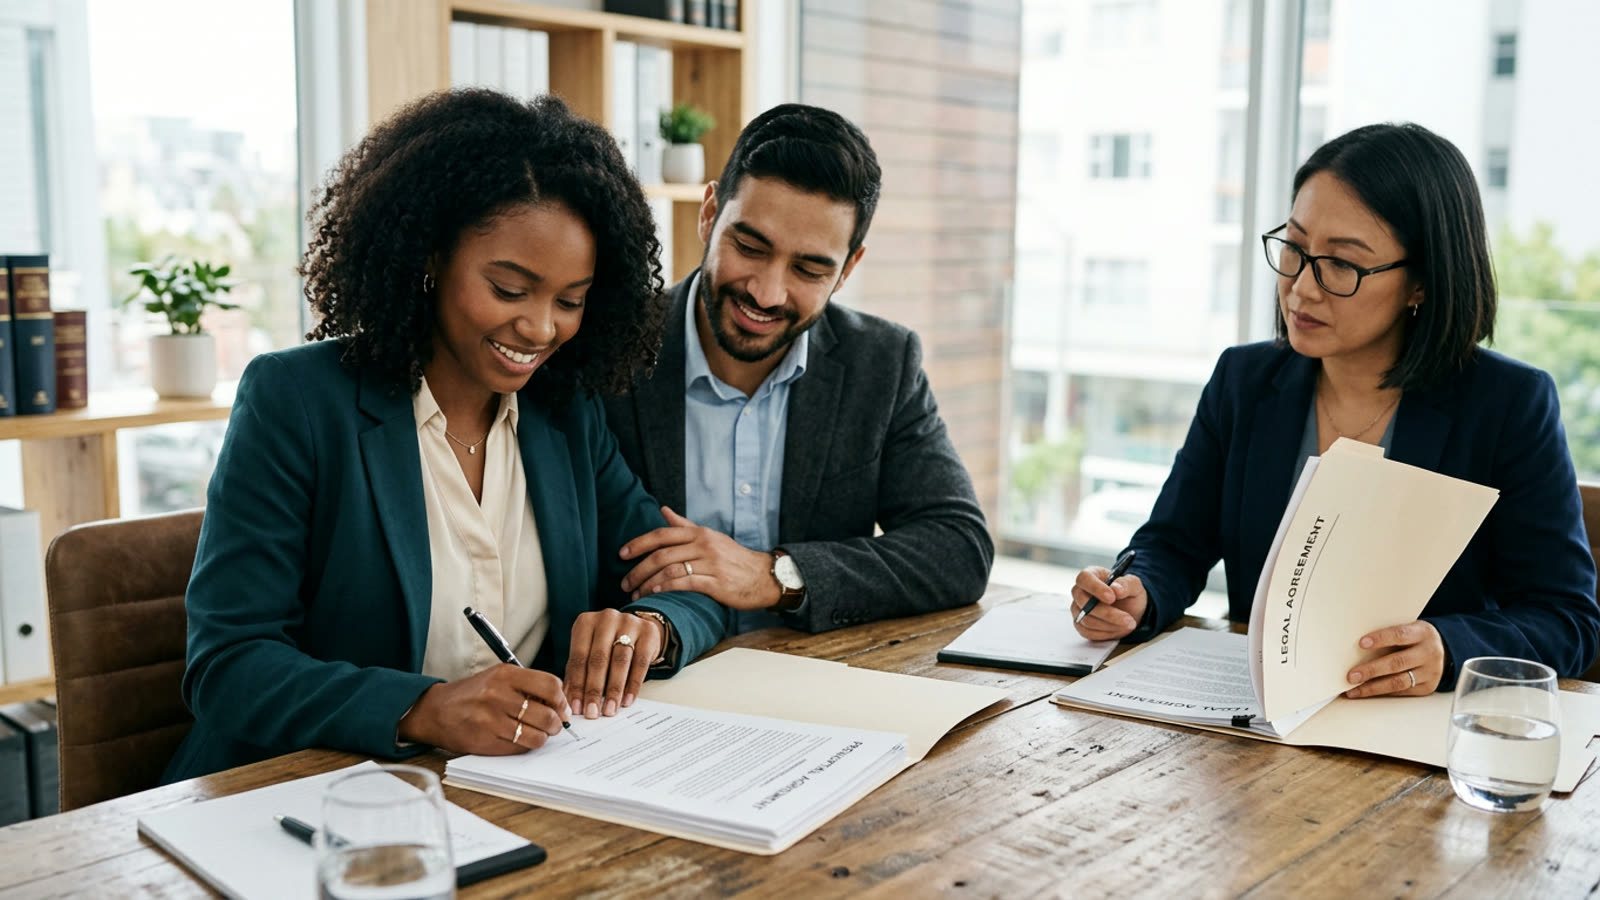
A prenuptial agreement, often called a prenup, is a legal contract signed by two people before marriage. It can address how property, debts and certain financial matters will be handled during the marriage and if the marriage ends through divorce or death.
Without a prenup, state law determines how property is divided in a divorce. States follow either community property rules, under which most property acquired during marriage is generally considered jointly owned and divided equally, or equitable distribution rules, under which property is divided in a way the court considers fair, which isn’t necessarily equal. A prenup allows couples to make their own decisions rather than relying entirely on state default rules.
Rules governing prenups vary by state. Many states have adopted the Uniform Premarital Agreement Act or a similar framework, but details differ.
Who often considers a prenup
Couples consider prenups for many reasons. One partner may have significant assets or a much higher income. One partner may own a business or a share of a family business, and wants to protect it. Either partner may have children from a previous relationship and want to protect assets for those children. Either may expect a significant inheritance. One partner may have significant debt, and the other wants to avoid responsibility for it.
Couples marrying later in life, after accumulating assets, and those who’ve been through a previous divorce also often consider prenups.
What a prenup can cover
Prenups can address a wide range of financial matters. They can specify which assets remain separate property, such as assets each partner brings into the marriage, inheritances, gifts or a business. They can determine how property acquired during the marriage is divided in a divorce. They can assign responsibility for debts, protecting each partner from the other’s premarital debts. They can protect a family business, preventing it from being divided in a divorce. They can address spousal support, or alimony, within the limits allowed by state law. And they can address what happens to property upon death, coordinating with estate plans.
Prenups can also address how finances will be managed during the marriage, though such provisions can be harder to enforce.
What a prenup generally can’t cover
Prenups generally can’t decide child custody or child support. Courts determine these based on the best interests of the child at the time of a divorce, and parents can’t waive a child’s right to support. Prenups also generally can’t include provisions that are illegal, encourage divorce or are unconscionable. Personal matters, like who does household chores, are generally not enforceable.
Making a prenup fair and valid
For a prenup to be enforceable, it generally must meet certain requirements. Following best practices helps ensure your agreement holds up.
Start early, well before the wedding. Signing a prenup days before the wedding may raise questions about whether it was signed voluntarily. Many attorneys recommend finalizing a prenup weeks or months before the wedding.
Fully disclose assets, debts and income. Both partners should provide complete, honest financial disclosure. Hiding assets can invalidate a prenup.
Each partner should have an independent attorney. Having separate lawyers helps ensure each person understands the agreement and their rights, and makes the agreement more likely to be upheld.
Avoid pressure. Agreements signed under duress, coercion or undue pressure may not hold up in court. Both partners should enter the agreement voluntarily.
Make it in writing and signed by both partners, following your state’s formal requirements.
Make sure the terms are reasonable. Agreements that are extremely one-sided or leave one partner in severe hardship may be challenged.
Review and update the agreement as circumstances change, such as after having children or significant changes in wealth. Some prenups include provisions for review or expiration.
How to bring it up
Raising the topic of a prenup can feel awkward. Approaching the conversation with honesty, respect and a focus on shared goals can help. Explaining your reasons, such as protecting children from a previous marriage or a family business, and emphasizing that it’s about clarity rather than distrust can make the conversation easier. Discussing it early, rather than close to the wedding, gives both partners time to consider it thoughtfully.
Talk openly about money
Even if you decide not to sign a prenup, discussing money, goals and expectations before marriage is valuable. Conversations about income, debts, spending habits, saving goals, financial values and how you’ll manage money together can strengthen your relationship and prevent future conflict. Many couples find that the process of discussing a prenup, whether or not they sign one, leads to healthier financial communication.
Content on The Evergreen Edit is for educational and informational purposes only and is not individualized financial, investment, tax or legal advice. Learn more.
This article is for educational purposes only and isn't personalized financial, tax or legal advice. Consider talking with a qualified professional about your situation.

Kiara Miller — Founder & Editor
Kiara Miller is the founder and editor of The Evergreen Edit. He has been doing independent finance research for two decades and reviews every article before it's published.
More about Kiara →Get smarter about your money.
Join readers who get The Sunday Edit every week.