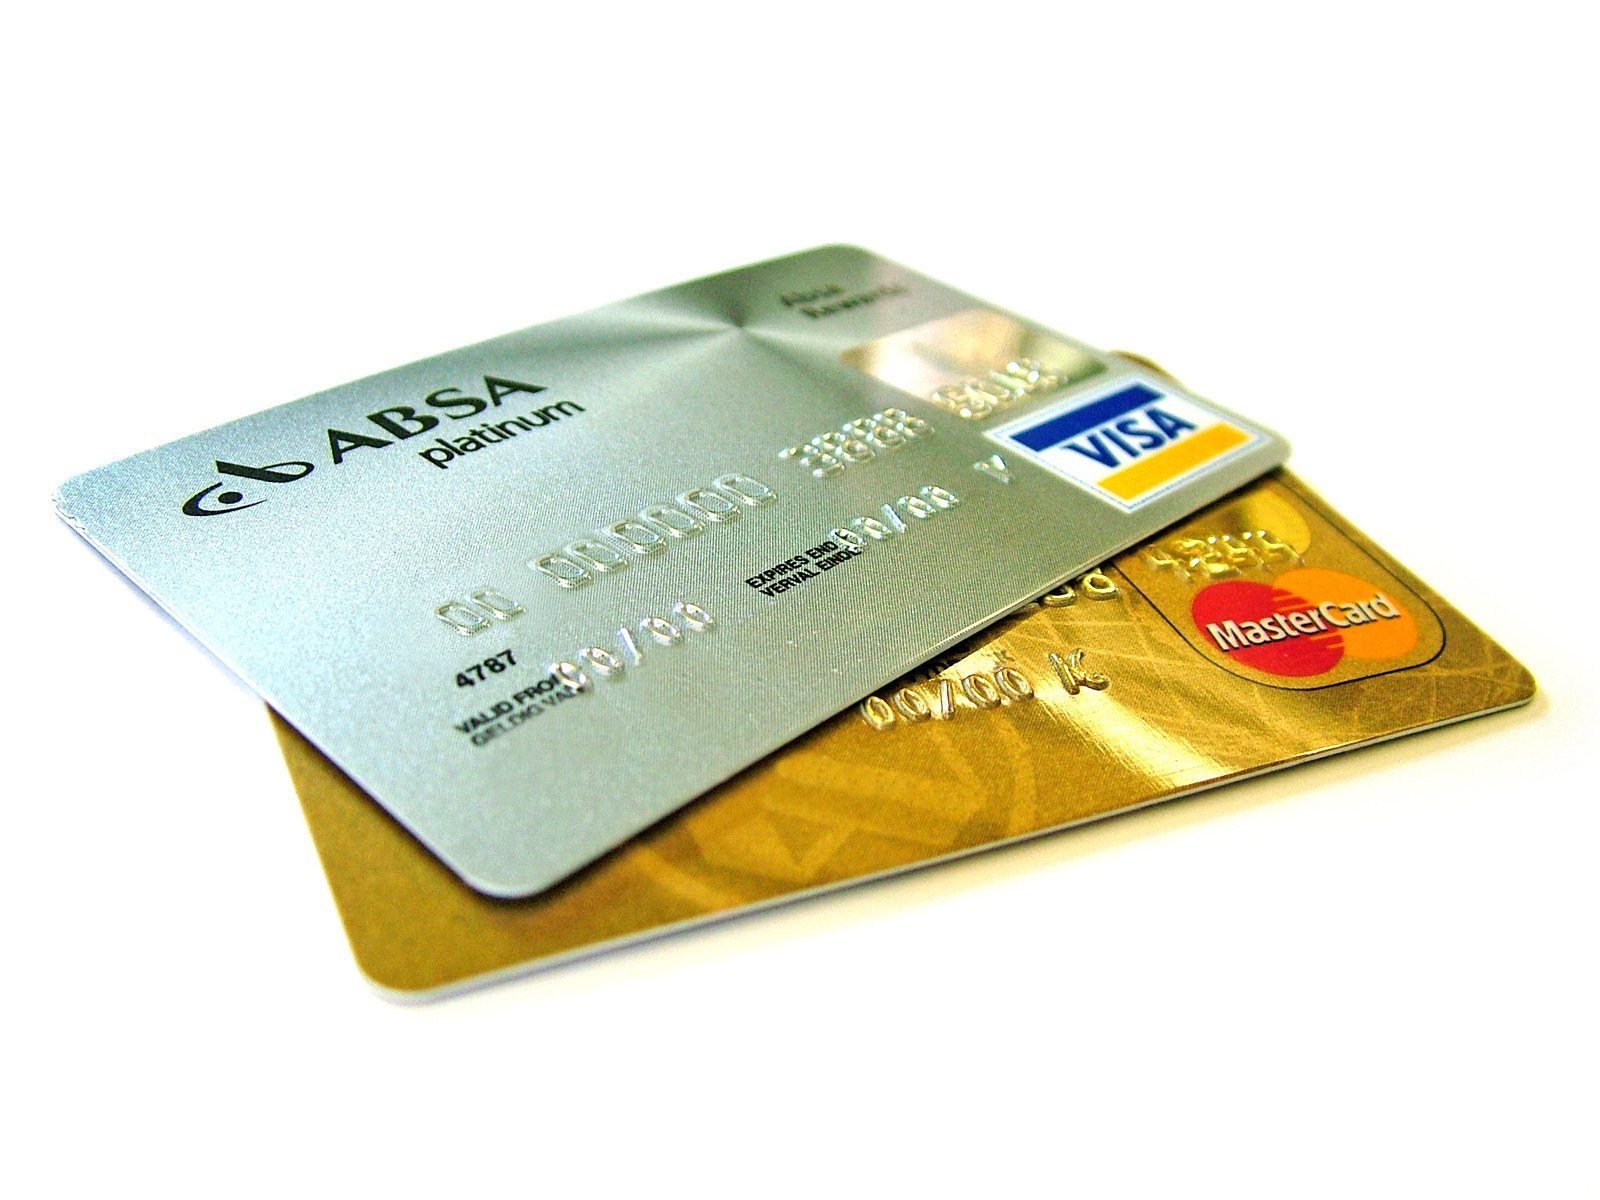

The minimum payment keeps your account in good standing, but it's built to shrink as your balance shrinks. Knowing the formula shows you exactly what an extra $10 or $50 a month buys.
How is a credit card minimum payment calculated?
Most issuers set the minimum as a small percentage of your statement balance, often 1%, plus that month's interest and any late fees, with a dollar floor, such as $40 at some issuers. Others use a flat percentage of the whole balance. Your card agreement and monthly statement spell out the exact formula your issuer uses.
Chase, for example, says that in most cases it calculates the minimum as $40 or 1% of the statement balance plus interest and late fees, whichever is greater, and that if your balance is under $40 the minimum is the full balance. Capital One describes the two common approaches in general terms: a percentage of the balance plus new interest and late fees, or a flat percentage of the entire balance, sometimes with any past-due amount added on top.
Those formulas weren't always this tight. According to a Congressional Research Service report, the average minimum payment fell from about 5% of the balance in the 1970s to about 2% by 2000. In January 2003, federal bank regulators issued guidance saying they expected minimum payments to "effectively amortize the current balance over a reasonable period of time," meaning each payment should actually chip away at the debt. They were worried about negative amortization, where a minimum is so small that interest and fees make the balance grow even when you pay on time.
The three parts of a typical minimum payment
It helps to break a "1% plus interest" minimum into its pieces, because each one behaves differently.
The first piece is principal, the 1% of your balance. On a $5,000 balance, that's $50. This is the only part of the payment that is guaranteed to reduce what you owe.
The second piece is interest. The Consumer Financial Protection Bureau explains that many issuers calculate interest daily using your average daily balance and a daily periodic rate, which is your APR divided by the number of days in the year. For a rough monthly estimate, you can divide the APR by 12. At a 22% APR, that's about 1.83% a month, or roughly $91.67 on $5,000.
The third piece is fees. A late fee from last month gets added to this month's minimum, which is one reason a single missed payment can make the next bill noticeably bigger.
Add the first two together and the minimum on a $5,000 balance at 22% is about $141.67. That sounds like real progress, but only $50 of it, a bit more than a third, reduces the debt. The rest pays the interest you were charged that month.
Worked example: $5,000 at 22% APR
To see how this plays out, we ran the numbers on a $5,000 balance at a 22% APR, which is close to the 2026 average for card accounts that paid interest in the Federal Reserve's consumer credit data. The example assumes the card's minimum is the greater of $40 or 1% of the balance plus interest, that no new purchases or fees are added, and that interest is figured monthly at one-twelfth of the APR. Real statements use daily balances, so your issuer's figures will differ slightly, but the pattern holds.
If you pay only the minimum each month, the first payment is about $141.67. Because the minimum is tied to the balance, it falls as the balance falls: about $125.57 a year later and about $77.52 after five years. It finally reaches the $40 floor after roughly 10 and a half years. In total, it takes 184 months, a little over 15 years, to pay off the card. You pay about $7,460 in interest, so the $5,000 balance costs about $12,460.
Now keep everything the same, but pay a fixed $141.67 every month, the size of that first minimum, instead of letting the payment shrink. The card is paid off in 58 months, just under five years, with about $3,121 in interest. Nothing about the card changed. The difference, about $4,340 in interest and roughly 10 years, comes entirely from refusing to let the payment shrink.
Here is how a few other fixed payments compare on the same $5,000 at 22%:
- $150 a month: paid off in 52 months, about $2,798 in interest
- About $191 a month: paid off in 36 months, about $1,874 in interest
- $200 a month: paid off in 34 months, about $1,750 in interest
- $250 a month: paid off in 26 months, about $1,286 in interest
The jump from the minimum to a steady $150 does most of the work. Each extra step still helps, but by less, because the faster you pay, the less time interest has to build.
Why a flat-percentage minimum can be even slower
Some cards use a flat percentage of the balance instead of "1% plus interest." That can work out fine at a higher percentage, but the math gets uncomfortable when the percentage is close to the monthly interest rate.
Take the same $5,000 at 22% with a minimum of 2% of the balance. The first payment is $100, but about $91.67 of it is interest, so the balance drops by only about $8. As the balance slowly falls, the payment falls with it. In our calculation, paying only that minimum would take more than 80 years and cost over $43,000 in interest. A 3% minimum on the same card would take about 17 years and cost about $7,014. This is the problem the 2003 guidance was aimed at, and it's why it pays to look up your card's exact formula rather than assume.
Read the minimum payment warning on your statement
You don't have to run these numbers yourself. Federal rules in Regulation Z require most credit card statements to include a Minimum Payment Warning box. It must say that if you make only the minimum payment each period, you will pay more in interest and it will take longer to pay off your balance. It must also show:
- how long it would take to pay off your current balance with minimum payments only;
- the total you'd pay that way; and
- a toll-free number for credit counseling information.
When paying only the minimum would take more than three years, the statement also generally shows the monthly payment needed to pay the balance off in about 36 months, the total cost at that payment and how much you'd save compared with paying the minimum. The estimates assume you add nothing new to the card. Some statements skip the box, for example when you paid in full the two previous months or when the minimum due pays off the entire balance.
That 36-month figure is a useful ready-made target. On our $5,000 example, it would be about $191 a month.
Where your extra payment goes
If your card carries more than one balance, such as purchases at one APR and a cash advance or expired promotional balance at another, it matters where your money lands. Under federal rules, any amount you pay above the minimum generally has to go to the balance with the highest APR first, then to the others in order of rate, with some exceptions, such as certain deferred-interest balances. The rules don't control how the issuer applies the minimum payment itself, so that part follows your card's terms. In practice, paying even a little more than the minimum is the part of your payment you can be sure goes to your most expensive debt first.
A simple plan to get ahead of the minimum
You don't need a perfect budget to beat the minimum. A few steps cover most of it.
- Find your formula and your rate. Look at your statement or card agreement for how the minimum is calculated and your current APR. Note the payoff time in the Minimum Payment Warning box.
- Freeze your payment. Take this month's minimum and commit to paying at least that amount every month, even as the required minimum falls. In our example, that one change cut the payoff time from about 15 years to about five.
- Set it on autopay. Many issuers let you schedule a fixed dollar amount instead of the minimum. Paying on time also avoids late fees, which get added to the next minimum.
- Add small raises. Any extra, even $10 or $25 a month, goes straight to principal once interest is covered. Some people add part of every raise or tax refund.
- Stop adding to the balance if you can. The payoff math above assumes no new charges. New purchases at the same APR stretch the timeline back out.
If you have several cards, a payoff method helps you decide where extra money goes first. Our guide to the debt snowball vs. the debt avalanche compares the two main approaches. If the interest rate itself is the problem, a balance transfer card or other lower-rate option may be worth comparing, keeping in mind transfer fees and what happens when a promotional rate ends. And for more on how the rate behind all of this works, see our explainer on credit card interest and APR.
When the minimum is all you can manage
Sometimes paying the minimum is the right call for a month or two. It keeps the account current, which protects your credit and avoids late fees and penalty rates. If you're there, it can help to call your issuer and ask what options it has, and to use the credit counseling number on your statement to find help with a budget or a repayment plan. What usually gets people into trouble isn't one month at the minimum, but years of it without a plan to move past it.
Frequently asked questions
What happens if I only pay the minimum on my credit card?
Your account stays in good standing, but most of each payment goes to interest and the balance falls slowly. Your statement's Minimum Payment Warning shows how long payoff would take and the total cost.
Why does my minimum payment go down every month?
Most minimums are calculated as a percentage of your current balance plus interest, so as the balance shrinks, the minimum shrinks too. Keeping your payment at a fixed amount instead speeds up payoff.
Where does a payment above the minimum go if I have more than one APR?
Under federal rules, the amount above the minimum generally goes to the balance with the highest APR first, with some exceptions such as certain deferred-interest balances.
Sources
- Chase, How to calculate your minimum credit card payment, 2026
- Capital One, Credit card minimum payments: What to know, January 15, 2026
- Congressional Research Service, Credit Card Minimum Payments (RS22352), April 4, 2008
- Consumer Financial Protection Bureau, How does my credit card company calculate the amount of interest I owe?, January 22, 2024
- Federal Reserve, Consumer Credit G.19, October 7, 2026
- Consumer Financial Protection Bureau, Regulation Z § 1026.7 Periodic statement
- Consumer Financial Protection Bureau, Regulation Z § 1026.53 Allocation of payments
Content on The Evergreen Edit is for educational and informational purposes only and is not individualized financial, investment, tax or legal advice. Learn more.
Your savings goal
Months to your goal: 45
Estimate only. No interest, fees or changes in contributions assumed.
This article is for educational purposes only and isn't personalized financial, tax or legal advice. Consider talking with a qualified professional about your situation.
Kiara Miller — Founder & Editor
Kiara Miller is the founder and editor of The Evergreen Edit. He has been doing independent finance research for two decades and reviews every article before it's published.
More about Kiara →Get smarter about your money.
Join readers who get money stories on their chosen topics, daily or as new articles post.