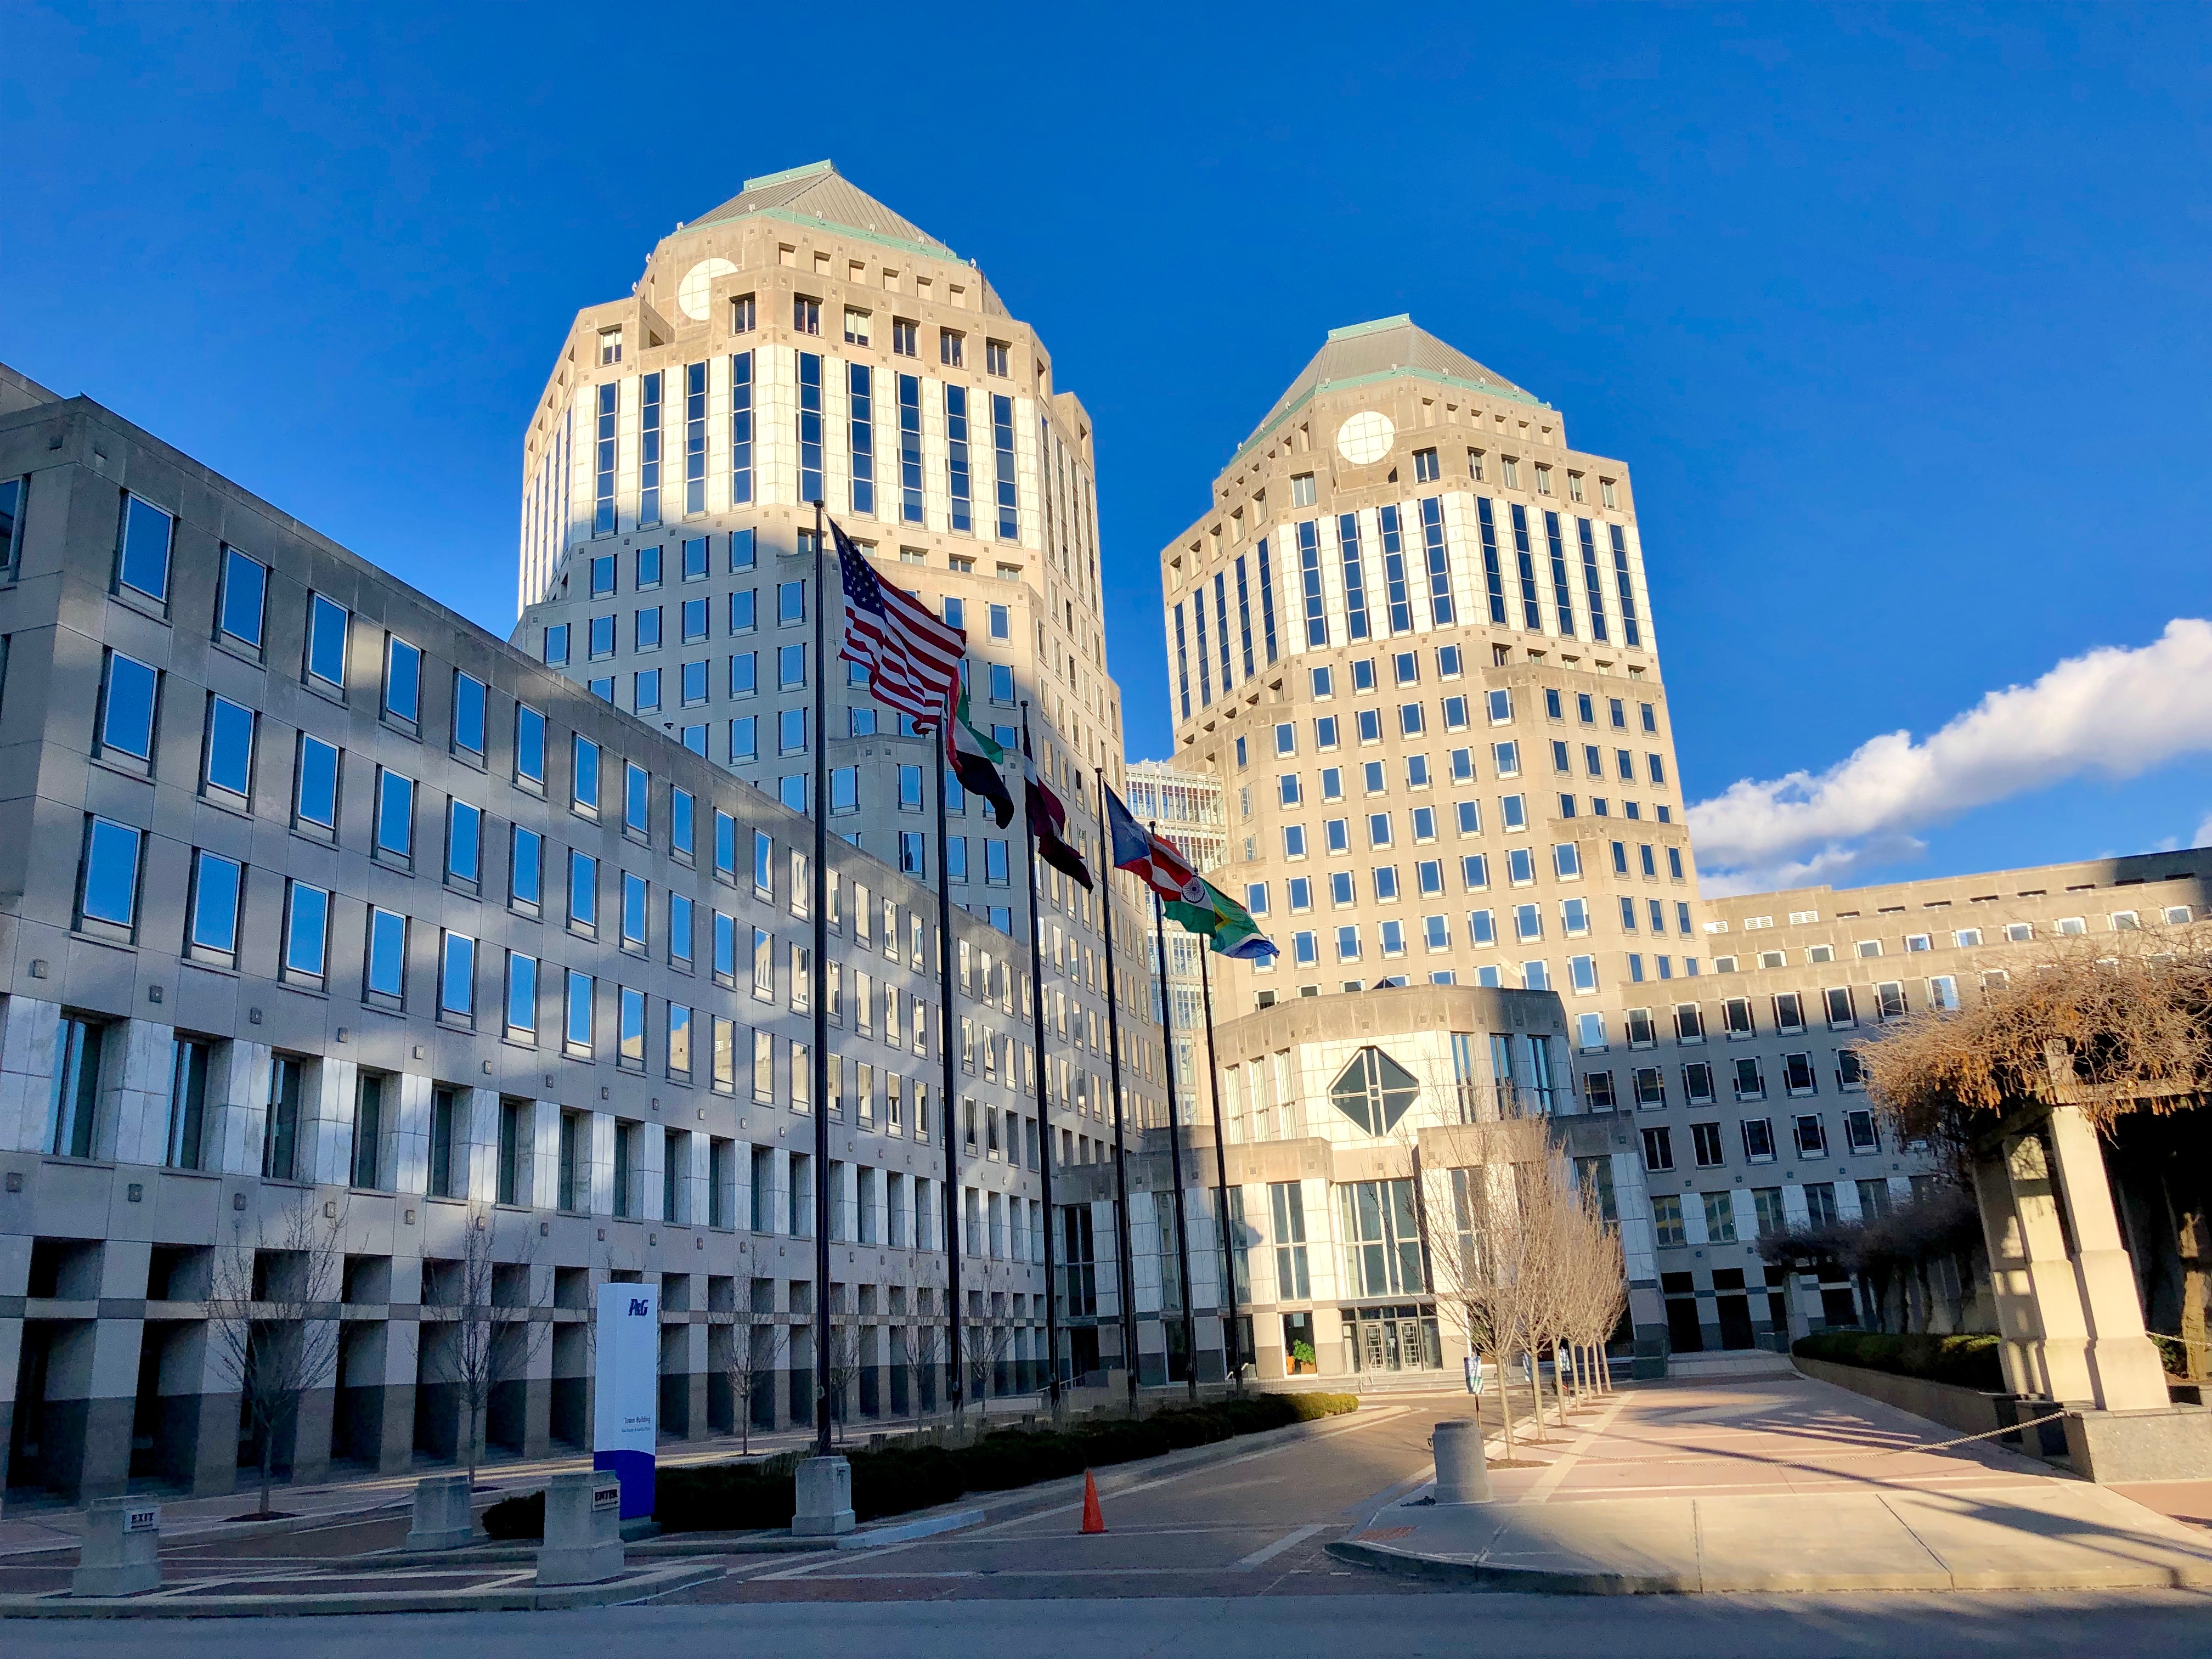
Procter & Gamble's latest earnings offer a useful reality check for dividend investors: recognizable brands and rising sales do not eliminate cost pressure. In results released October 22, 2026, the company reported stronger revenue but much slower earnings growth. The distinction matters if you own consumer-staples stocks for dependable income rather than rapid expansion.
P&G reported fiscal first-quarter 2027 net sales of $23.3 billion, up 4% from a year earlier. Organic sales also grew 4%. Diluted earnings per share rose 1% to $1.97, while core earnings per share increased 1% to $2.00. The quarter covered July through September 2026; the fiscal-year label does not mean these are results from calendar 2027.
Sales improved for more than one reason
Organic sales remove the effects of currency changes and acquisitions or divestitures, helping readers compare the underlying business. P&G said volume contributed roughly two percentage points to growth and favorable product mix contributed roughly one point, while pricing had a minor positive effect. That suggests the improvement was not simply a story of charging more for the same volume.
The company reported rounded organic sales growth of 5% in Beauty, Grooming, and Fabric & Home Care, and 3% in Health Care and Baby, Feminine & Family Care. Those divisions cover products consumers regularly buy, but demand still depends on affordability, competition and the perceived value of premium brands.
A familiar product on a household shelf is not proof that the stock is attractively priced. Investors need to distinguish a strong business from a strong investment at today's valuation. A dependable company can deliver disappointing returns if the purchase price assumes more…
Unlock the full analysis
See the weekly membership price and unlock the full analysis.
See weekly checkoutSee all plansAlready a member? Sign in
Content on The Evergreen Edit is for educational and informational purposes only and is not individualized financial, investment, tax or legal advice. Learn more.
Compound growth estimate
Estimated total
$17,175
Your contributions
$13,000
This is an estimate, not a prediction. Monthly compounding; taxes, fees and inflation are excluded.
This article is for educational purposes only and isn't personalized financial, tax or legal advice. Consider talking with a qualified professional about your situation.
Kiara Miller — Founder & Editor
Kiara Miller is the founder and editor of The Evergreen Edit. He has been doing independent finance research for two decades and reviews every article before it's published.
More about Kiara →Get smarter about your money.
Join readers who get money stories on their chosen topics, daily or as new articles post.