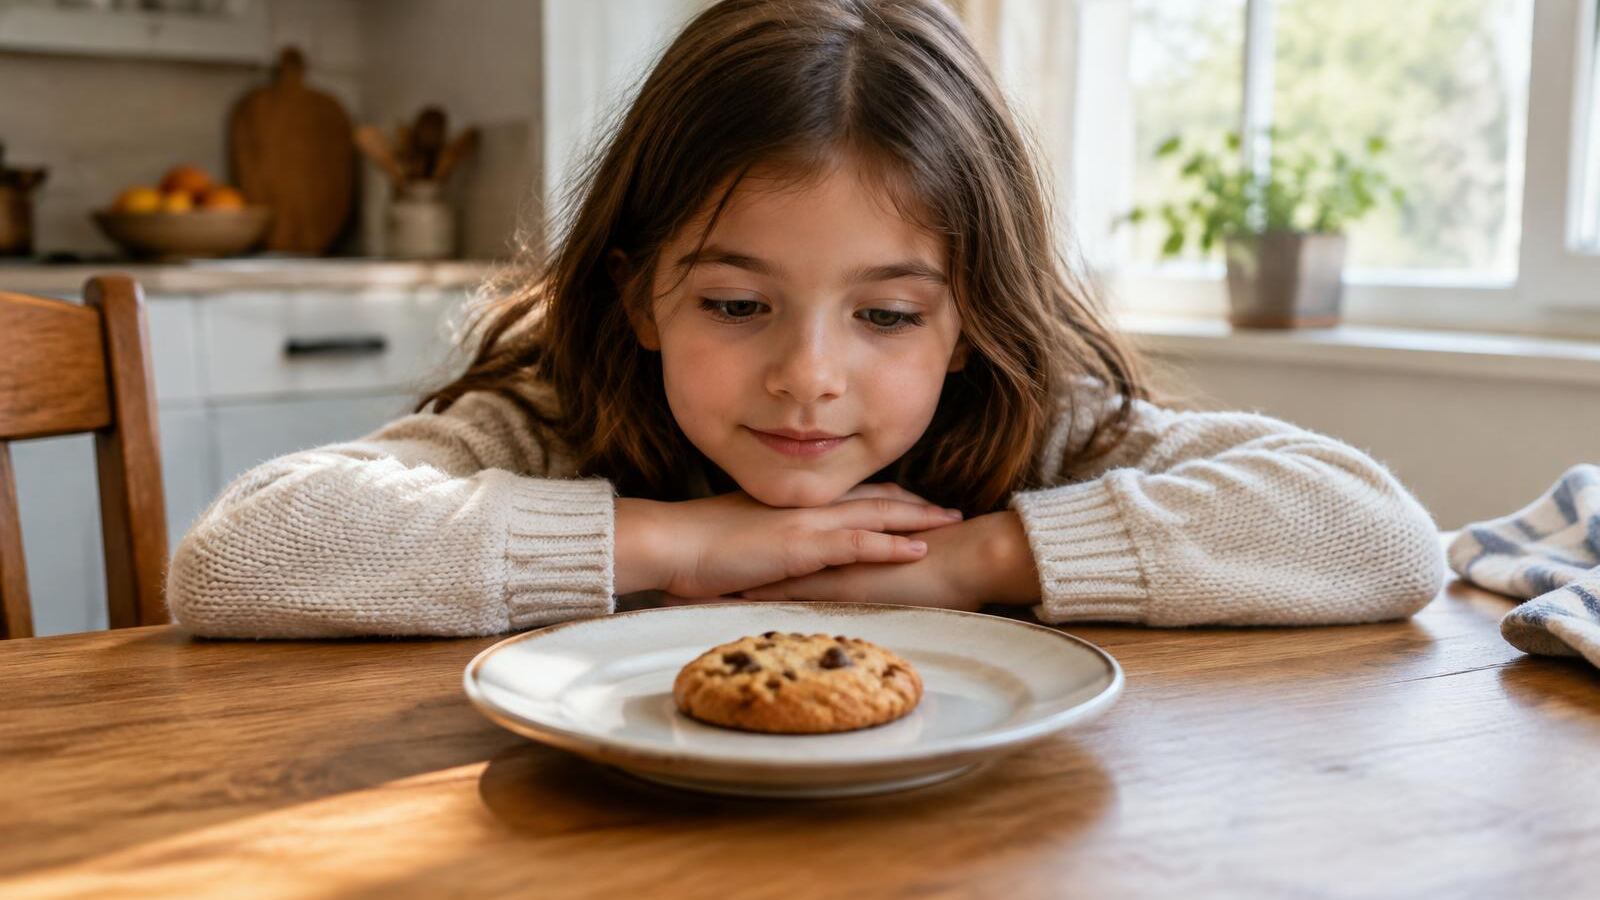
You’ve probably heard of the marshmallow test, a famous series of studies in which young children were offered a choice: one treat now, or two treats if they could wait a short time. Early research suggested that children who waited tended to have better outcomes later in life. Later research has added nuance to what those studies mean, suggesting that factors like family background and environment play important roles. But the core idea still applies to money: the ability to wait for something better can make a big difference in building wealth.
Why waiting is so hard
Our brains tend to value rewards now more than rewards later. A new gadget today feels concrete and exciting, while a bigger retirement account in 30 years feels abstract and distant. Psychologists and economists call this tendency present bias.
Present bias helps explain why people often struggle to save, even when they know saving is important. The benefits of saving are delayed and uncertain, while the pleasures of spending are immediate. Marketers understand this well, which is why offers emphasize instant gratification, such as buy now, pay later, same-day delivery and one-click purchasing.
Why delayed gratification builds wealth
Delayed gratification is at the heart of building wealth. Money you save and invest today can grow through compound interest, where your earnings generate their own earnings over time. Choosing to save rather than spend allows that growth to happen.
For example, money invested in your 20s has decades to compound, potentially growing into a much larger sum by retirement. Avoiding debt by waiting to buy things until you can afford them also saves money, since you avoid interest charges.
Make the future feel real
Because future rewards feel abstract, making them more concrete can help you resist immediate temptations.
Set specific goals with a picture or name. Instead of saving for savings, save for a beach trip in June, a down payment on a home or a debt-free life by a specific date. Giving your goals names and images makes them more vivid and motivating.
Track progress visually, such as by shading boxes on a savings chart or watching a progress bar in a savings app. Seeing progress toward your goal makes the future reward feel closer.
Calculate what money saved today could grow into using a simple compound interest calculator. Seeing how a modest monthly contribution could grow over decades can make the trade-off between spending now and saving for later more tangible.
Some people find it helpful to imagine their future selves in detail, picturing the life they want and the security they’ll have. Research suggests that feeling connected to your future self can encourage saving.
Change your environment
Willpower is limited and tends to be weakest when you’re tired, stressed or hungry. Rather than relying on willpower alone, change your environment to make waiting easier.
Unsubscribe from store emails and delete shopping apps, reducing constant temptations.
Remove saved card numbers from websites, adding friction that gives you a moment to reconsider purchases.
Use a waiting rule, such as waiting 24 hours for small purchases or 30 days for larger ones. Often, the desire for an item fades during the waiting period, and you’ll realize you don’t really need it. If you still want it after waiting, you can buy it with more confidence.
Automate savings so money moves to savings before you can spend it. When saving happens automatically on payday, you don’t have to resist the temptation to spend that money.
Reward yourself along the way
Delayed gratification doesn’t mean no gratification. A plan that requires constant sacrifice is hard to sustain and can lead to burnout or splurges. Build small, affordable rewards into your plan, and celebrate milestones as you reach them.
Including some joy in your budget, such as a modest fun-money category for things you enjoy, makes it easier to stick with your long-term plan. Balance is key: enjoying life today while building security for tomorrow.
Practice makes it easier
Delayed gratification is a skill that can be strengthened with practice. Each time you choose to wait or save, you reinforce the habit. Over time, choosing long-term rewards can become more natural, and the satisfaction of reaching your goals can become its own reward.
Context matters
Waiting is much easier when your basic needs are secure. Research on the marshmallow test and related studies suggests that people who face uncertainty or scarcity may reasonably prefer immediate rewards, since future rewards may not feel reliable.
If money is very tight, focus first on stability, covering essential expenses and building a small emergency buffer. Even a modest cushion can reduce stress and make it easier to plan for the future. Delayed gratification becomes more achievable as your financial foundation becomes more secure.
Content on The Evergreen Edit is for educational and informational purposes only and is not individualized financial, investment, tax or legal advice. Learn more.
This article is for educational purposes only and isn't personalized financial, tax or legal advice. Consider talking with a qualified professional about your situation.

Kiara Miller — Founder & Editor
Kiara Miller is the founder and editor of The Evergreen Edit. He has been doing independent finance research for two decades and reviews every article before it's published.
More about Kiara →Get smarter about your money.
Join readers who get The Sunday Edit every week.