Imagine finding $100 on the sidewalk, then later losing $100 from your wallet. Financially, you’re back where you started. But for many people, the pain of losing the $100 would feel stronger than the joy of finding it. That tendency is called loss aversion, and it can quietly shape many of our money decisions, from investing to shopping.
Where the idea comes from
Psychologists Daniel Kahneman and Amos Tversky studied how people make decisions involving risk and uncertainty. Their research, part of what became known as prospect theory, found that people don’t evaluate gains and losses symmetrically. Instead, people tend to weigh potential losses more heavily than equivalent potential gains. Kahneman later received the Nobel Memorial Prize in Economic Sciences, in part for this work.
Research has suggested that losses can feel roughly twice as powerful, psychologically, as equivalent gains, though estimates vary across studies and situations. This asymmetry helps explain why people often make choices that avoid losses even when the alternative might lead to better outcomes.
Loss aversion may have evolutionary roots. For our ancestors, avoiding losses, such as losing food or shelter, may have been more important for survival than pursuing gains.
How loss aversion affects investing
Loss aversion can significantly affect investment decisions, often in ways that hurt long-term results.
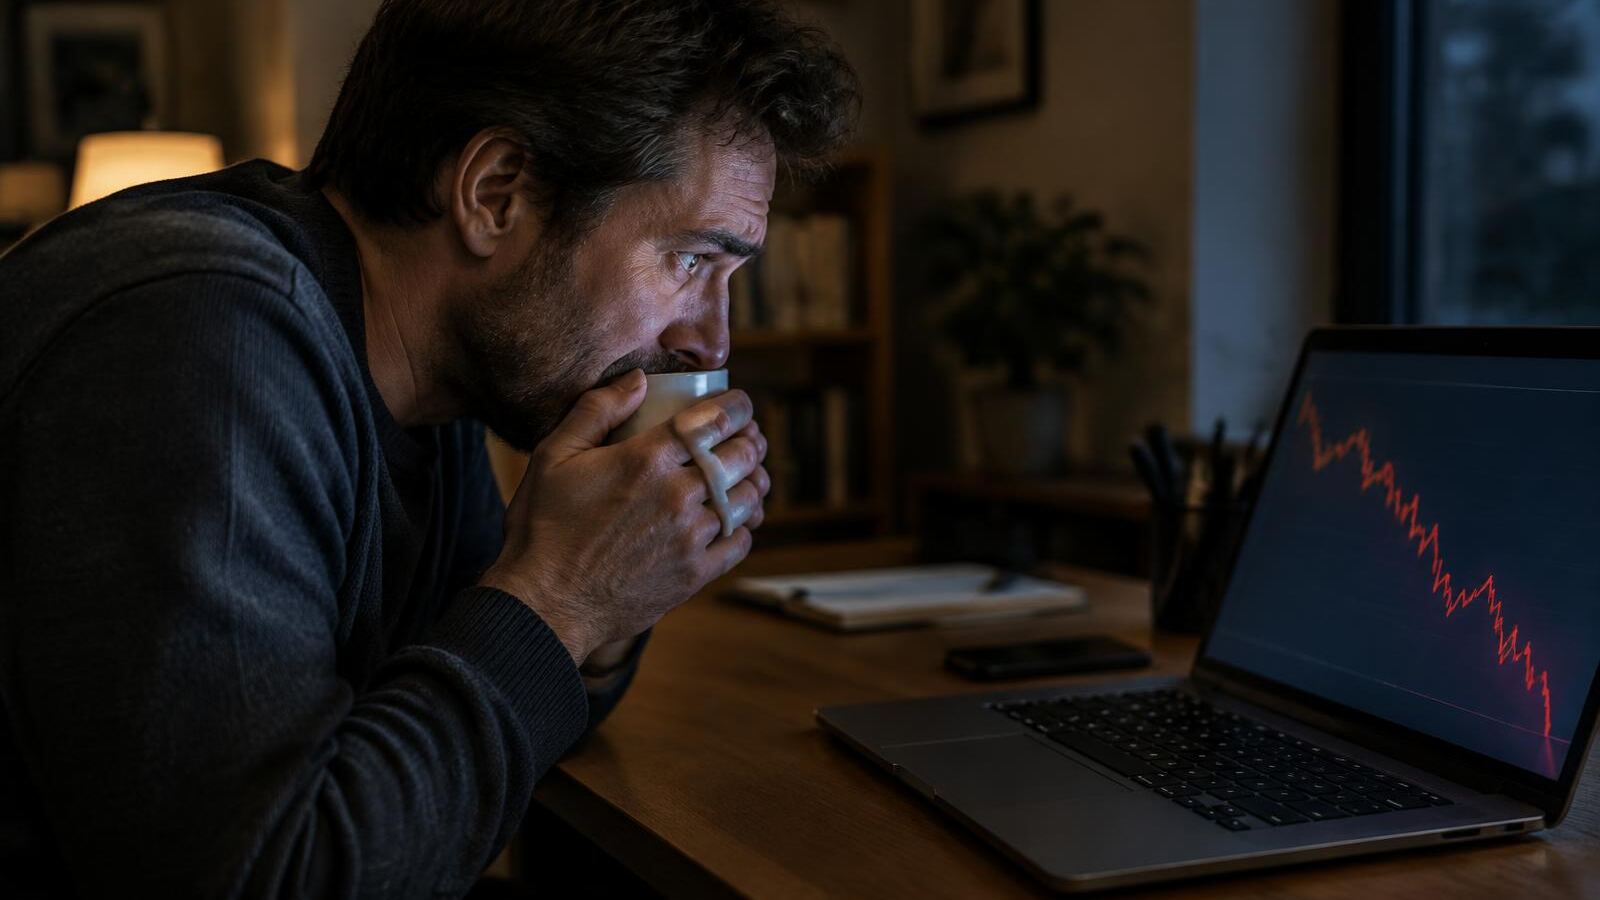
Panic selling is a common example. Seeing investments drop in value can feel so painful that people sell to stop the pain, locking in losses. By selling after prices fall, investors turn temporary paper losses into permanent ones and may miss the recovery when markets rebound.
Holding losers too long is another effect. Some investors keep losing investments much longer than they should, refusing to sell because selling would mean admitting the loss is real. They may hold on, hoping to break even, even when the investment’s prospects are poor. Meanwhile, they may sell winning investments too early to lock in gains. This pattern is sometimes called the disposition effect.
Too much caution can also result from loss aversion. Fear of losses can lead people to keep long-term money in cash or very conservative investments, missing out on potential growth. Over long periods, inflation can erode the purchasing power of cash, meaning excessive caution carries its own risk.
How loss aversion affects spending
Marketers understand that losses feel powerful, and they often frame offers to take advantage of loss aversion.
Phrases like don’t miss out, only two left, offer ends tonight or limited-time deal frame not buying as a loss. These messages create a sense of urgency and fear of missing out, which can push people to make purchases they might otherwise reconsider.
Free trials that convert to paid plans take advantage of our reluctance to give something up once we have it. After using a service for free, canceling can feel like losing something, even though we were happy without it before.
Money-back guarantees and generous return policies can encourage purchases, but once people own an item, they’re often reluctant to return it, a related tendency called the endowment effect, where people value things more once they own them.
Loss framing also appears in pricing, such as presenting a surcharge for paying by card versus a discount for paying cash, which can feel different even when the financial outcome is identical.
How to manage loss aversion
You can’t eliminate loss aversion entirely, since it’s a deeply rooted human tendency. But you can build habits and systems that reduce its influence.
Make a plan in advance. Decide on an investment mix you’ll stick with through ups and downs, based on your goals, timeline and risk tolerance. Having a plan created when you’re calm helps you avoid emotional decisions during market turbulence. Writing down your plan and the reasons behind it can help you stay the course.
Check long-term investments less often. Frequently checking your portfolio increases the chances of seeing losses, which can trigger anxiety and the urge to act. For long-term investments, checking periodically, such as quarterly or annually, is usually enough.
Automate good decisions. Automatic contributions and rebalancing reduce the number of decisions you need to make, limiting opportunities for loss aversion to influence you.
Pause before buying anything marketed as urgent. When you see limited-time offers or scarcity messages, take a step back. Most deals return, and genuinely good purchases will still make sense after some reflection.
Ask whether you’d buy the item at full price with no deadline. If the answer is no, the urgency may be driving your decision more than genuine need.
Evaluate investments on their future prospects, not their purchase price. The price you paid is irrelevant to whether an investment is a good holding today.
Understanding yourself
Recognizing loss aversion in your own behavior is a powerful first step. By understanding how this tendency influences your decisions, you can build strategies to make more balanced, rational financial choices that serve your long-term goals.
This article is for education only and isn’t investment advice.
Content on The Evergreen Edit is for educational and informational purposes only and is not individualized financial, investment, tax or legal advice. Learn more.
This article is for educational purposes only and isn't personalized financial, tax or legal advice. Consider talking with a qualified professional about your situation.

Kiara Miller — Founder & Editor
Kiara Miller is the founder and editor of The Evergreen Edit. He has been doing independent finance research for two decades and reviews every article before it's published.
More about Kiara →Get smarter about your money.
Join readers who get The Sunday Edit every week.