Many affluent parents share a common worry: that their children will grow up feeling entitled, unmotivated or disconnected from the value of money and hard work. Wealth can provide children with remarkable opportunities, but it can also create challenges that families with fewer resources don’t face. With thoughtful parenting, affluent families can raise children who appreciate their opportunities, develop strong values and build their own sense of purpose.
The challenges of growing up with wealth
Children in affluent families may never experience financial scarcity, which can make it harder to understand the value of money, the effort required to earn it or the trade-offs most people face. Without intentional guidance, some children may develop unrealistic expectations, lack motivation to build their own careers or struggle to find purpose.
Wealth can also create emotional challenges, such as uncertainty about whether others value them for themselves or their family’s wealth, pressure to live up to family success or anxiety about future responsibilities.
These challenges aren’t inevitable. Many children from affluent families grow up grounded, hardworking and generous, often because their parents were intentional about teaching values and responsibility.
Talk about money and values
Silence about money can create confusion. Children notice their family’s lifestyle and may draw their own conclusions without guidance. Talking openly about money, at a level appropriate for their age, helps children develop healthy attitudes.
Discuss what money means to your family, how it was earned and how you choose to use it. Sharing the story of how family wealth was built, including the hard work, risks and setbacks involved, can help children appreciate it and understand that wealth isn’t automatic.
Talk about your family’s values, such as hard work, generosity, education, integrity and responsibility, and how money connects to those values. Explain your choices, such as why you save, give to charity or decide not to buy certain things.
Be honest in age-appropriate ways. Young children need simple concepts, while teenagers can understand more about family finances, investing and responsibilities.
Let them practice with real money
Hands-on experience builds financial skills and appreciation for money.
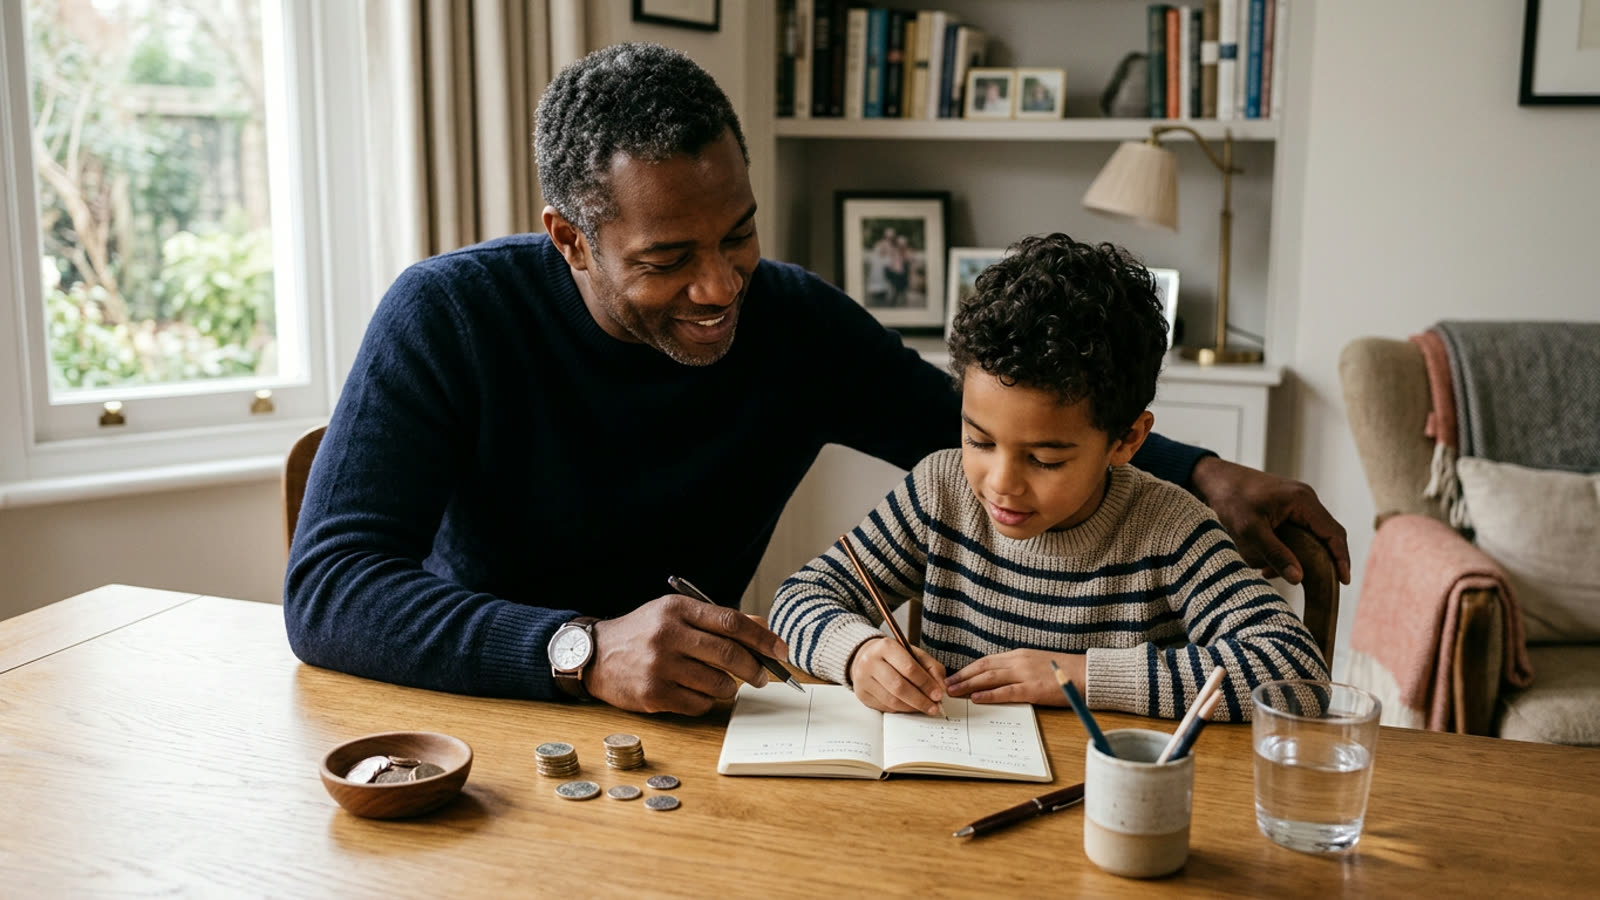
Give an allowance with real responsibilities. An allowance lets children practice budgeting, saving and making choices. As children grow, increase both the allowance and the expenses they’re responsible for, such as clothing or entertainment.
Encourage part-time jobs and summer work. Working teaches responsibility, the value of earning money, workplace skills and empathy for people in different circumstances. Even if a family doesn’t need the income, the experience can be invaluable.
Let kids save for goals instead of buying everything for them. Saving for something they want teaches patience, delayed gratification and the satisfaction of achieving goals through effort.
Allow small mistakes when stakes are low. Spending all their money on something they later regret is a valuable lesson best learned with small amounts during childhood rather than large sums as adults.
Teach stewardship and generosity
Involve children in family giving, such as choosing charities through a donor-advised fund or family foundation. Children can research causes, visit organizations and help decide how to allocate donations. Volunteering together as a family can deepen understanding of community needs and the impact of generosity.
Help children see wealth as a responsibility as well as a resource, a tool that can be used to support family, community and causes they care about. A sense of stewardship can give wealth deeper meaning and purpose.
Prepare the next generation
As children grow, gradually introduce investing and financial concepts, such as how compound growth works, how investment accounts function and how to evaluate financial decisions. Some families open custodial investment accounts or Roth IRAs for teens with earned income to teach investing hands-on.
Include older children in age-appropriate family meetings about finances, philanthropy or the family business. These meetings can build knowledge, communication skills and a sense of involvement.
Explain estate plans and expectations as children reach adulthood, including what they might inherit, how assets may be held in trust and the values that guide your plans. Clear communication can prevent surprises and unrealistic expectations.
Plan inheritances thoughtfully
Trusts can control when and how heirs receive assets, such as distributing portions at certain ages or milestones, supporting specific goals like education or home buying, or encouraging work and productivity. Some parents include incentives that reward education, employment or community service, though overly controlling provisions can create resentment.
An estate attorney can help design a plan that reflects your values and your children’s needs, balancing support with encouraging independence.
Model what you teach
Children learn most from watching how their parents handle money, work and generosity. If you value hard work, live within your means, treat others with respect regardless of wealth and give generously, your children are more likely to adopt those values. Your actions speak louder than any lesson.
Content on The Evergreen Edit is for educational and informational purposes only and is not individualized financial, investment, tax or legal advice. Learn more.
This article is for educational purposes only and isn't personalized financial, tax or legal advice. Consider talking with a qualified professional about your situation.

Kiara Miller — Founder & Editor
Kiara Miller is the founder and editor of The Evergreen Edit. He has been doing independent finance research for two decades and reviews every article before it's published.
More about Kiara →Get smarter about your money.
Join readers who get The Sunday Edit every week.