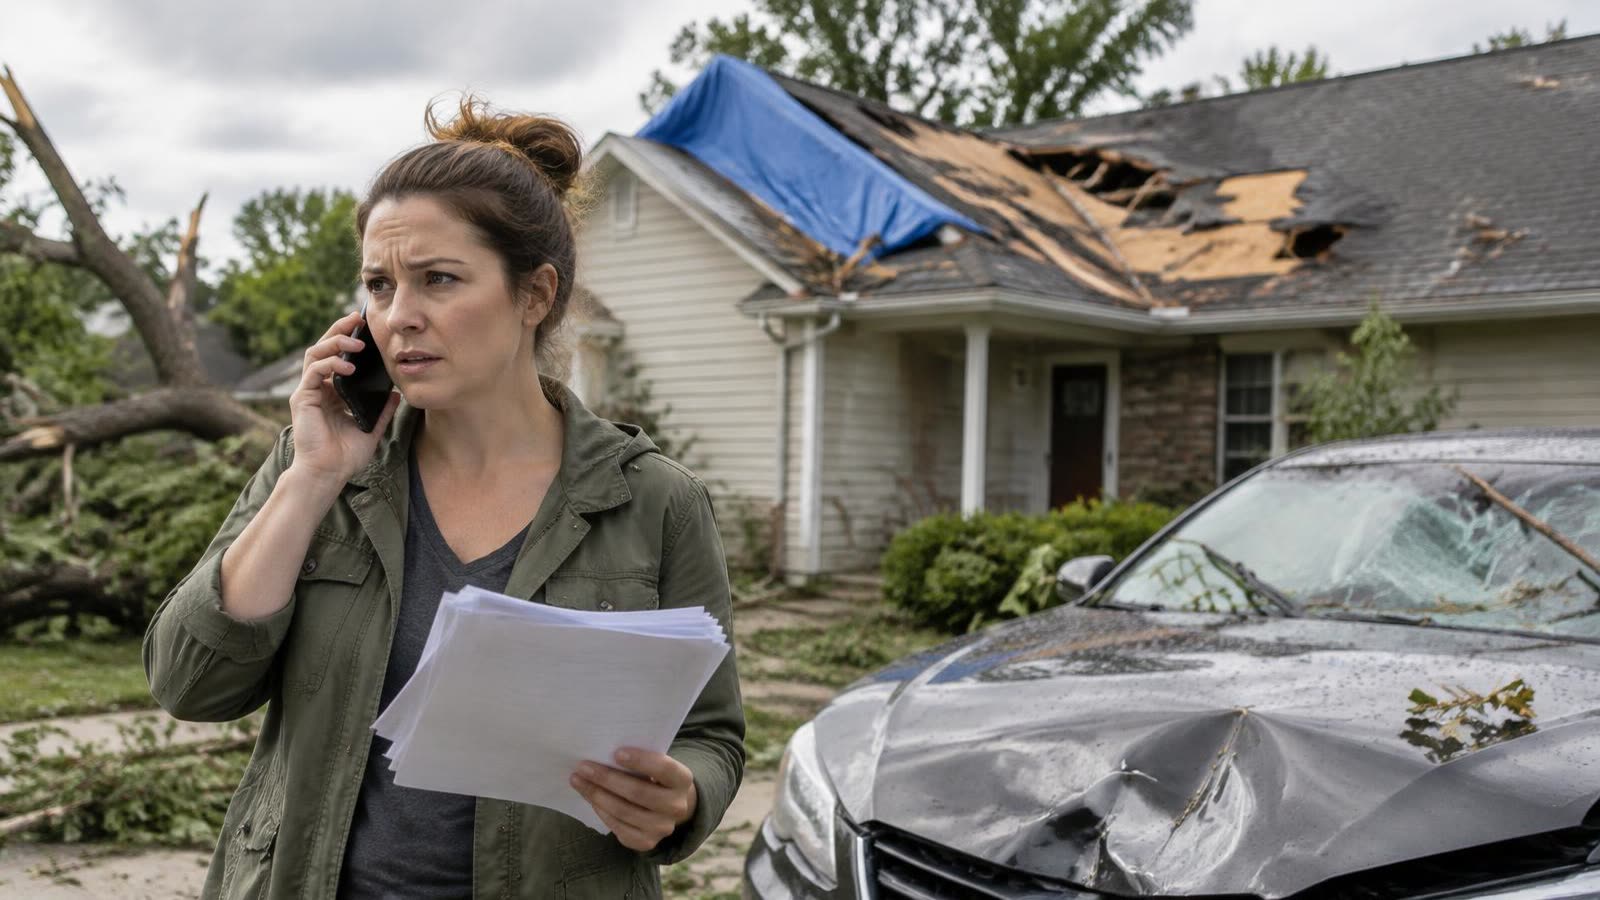
One of the country's biggest insurers just gave homeowners and drivers a useful peek at where insurance prices are heading.
Travelers reported third-quarter net income of $1.917 billion, or $9.04 a share, on Oct. 16, according to its earnings release. Core income, which strips out some investment gains and losses, was $9.18 a share. Catastrophe losses rose to $538 million before taxes, up from $402 million a year earlier, an increase of about 34%.
What happened in Travelers' third quarter?
Travelers beat expectations thanks to strong underwriting and a record $1.098 billion in investment income. But severe wind and hail storms in several states pushed catastrophe losses up about 34% to $538 million. Its shares slipped about 3% before the market opened Oct. 16, as investors focused on the storm losses and flat revenue.
The company's combined ratio, which compares claims and expenses with premiums, improved to 86.8% from 87.3%. Below 100% means an insurer is making money on its policies. CEO Alan Schnitzer called it "very strong underwriting performance across all three segments," according to Insurance Journal.
The part that matters for your wallet: renewal prices
Travelers' personal insurance figures show how much existing customers paid when they renewed, according to StockTitan's breakdown of the results:
- Auto: the average renewal premium fell 0.6% from a year earlier, after rising 3.9% in the same quarter of 2025.
- Home: the average renewal premium rose 5.4%, far slower than the 17.5% jump a year earlier.
- Policies: Travelers had about 2.77 million auto policies in force, down about 3%, and about 5.37 million home policies, down about 4%.
That fits a broader trend. The Bureau of Labor Statistics' measure of motor vehicle insurance prices was 5.0% lower in September than a year earlier, StockTitan noted. After two years of steep increases, car insurance is finally cooling, while home insurance is still rising, just more slowly.
What this could mean for your next bill
These are averages for one company. Your own premium depends on where you live, your car or home, your credit-based insurance score in most states and your claims history. Homeowners in storm-prone areas may still see bigger increases, since hail and wind losses are exactly what drove Travelers' catastrophe costs higher.
Here's a simple way to check whether your renewal is reasonable. If your auto policy cost $1,800 last year, a 0.6% drop would mean about $1,789. If your renewal comes in at $1,950, that's an 8% increase, well above the average, and a good reason to compare quotes.
Steps to take before you renew
- Read your renewal notice closely and compare the new premium with last year's.
- Get at least three quotes for the same coverage and deductibles, so you're comparing like with like.
- Ask about discounts for bundling home and auto, safe driving, home security or paying in full.
- Consider a higher deductible only if you have savings to cover it if you need to file a claim.
- Review your coverage limits, since rebuilding costs have risen and being underinsured can cost far more than a premium increase.
For a deeper look, read our guides to saving on car insurance without cutting coverage, what homeowners insurance covers and how to file a home insurance claim after a storm.
Frequently asked questions
How much did Travelers earn in the third quarter of 2026?
Travelers reported net income of $1.917 billion, or $9.04 a share, and core income of $1.947 billion, or $9.18 a share, for the quarter ended Sept. 30, 2026.
Why did Travelers' catastrophe losses rise?
The company said severe wind and hail storms in multiple states pushed pre-tax catastrophe losses to $538 million, up from $402 million a year earlier.
Are car insurance prices going down?
On average, they're cooling. Travelers' average auto renewal premium fell 0.6% from a year earlier, and the government's measure of motor vehicle insurance prices was down 5.0% year over year in September.
Is homeowners insurance still getting more expensive?
Yes, but more slowly. Travelers' average home renewal premium rose 5.4%, compared with 17.5% a year earlier.
Sources
Content on The Evergreen Edit is for educational and informational purposes only and is not individualized financial, investment, tax or legal advice. Learn more.
This article is for educational purposes only and isn't personalized financial, tax or legal advice. Consider talking with a qualified professional about your situation.

Kiara Miller — Founder & Editor
Kiara Miller is the founder and editor of The Evergreen Edit. He has been doing independent finance research for two decades and reviews every article before it's published.
More about Kiara →Get smarter about your money.
Join readers who get The Sunday Edit every week.