Automating your finances means your money moves where it should without you having to remember to do it. Bills get paid on time, savings grow every payday and investments happen in the background while you get on with your life.
It is one of the most effective ways to improve your finances because it removes the two biggest obstacles most people face: forgetting and willpower. And the setup can usually be done in a single afternoon.
Why automation works
Every manual financial task is a chance for something to go wrong. You might forget a bill and pay a late fee, or intend to save but spend the money first. Automation makes good decisions the default. You decide once how your money should flow, and the system carries out that decision every month.
Automation also reduces stress. Instead of juggling due dates in your head, you can trust that essentials are handled and focus your attention on bigger choices.
Map your money flow
Before you set anything up, think of your paycheck as the starting point of a stream that branches into several channels. Decide where each dollar should go: bills, savings, investments and everyday spending.
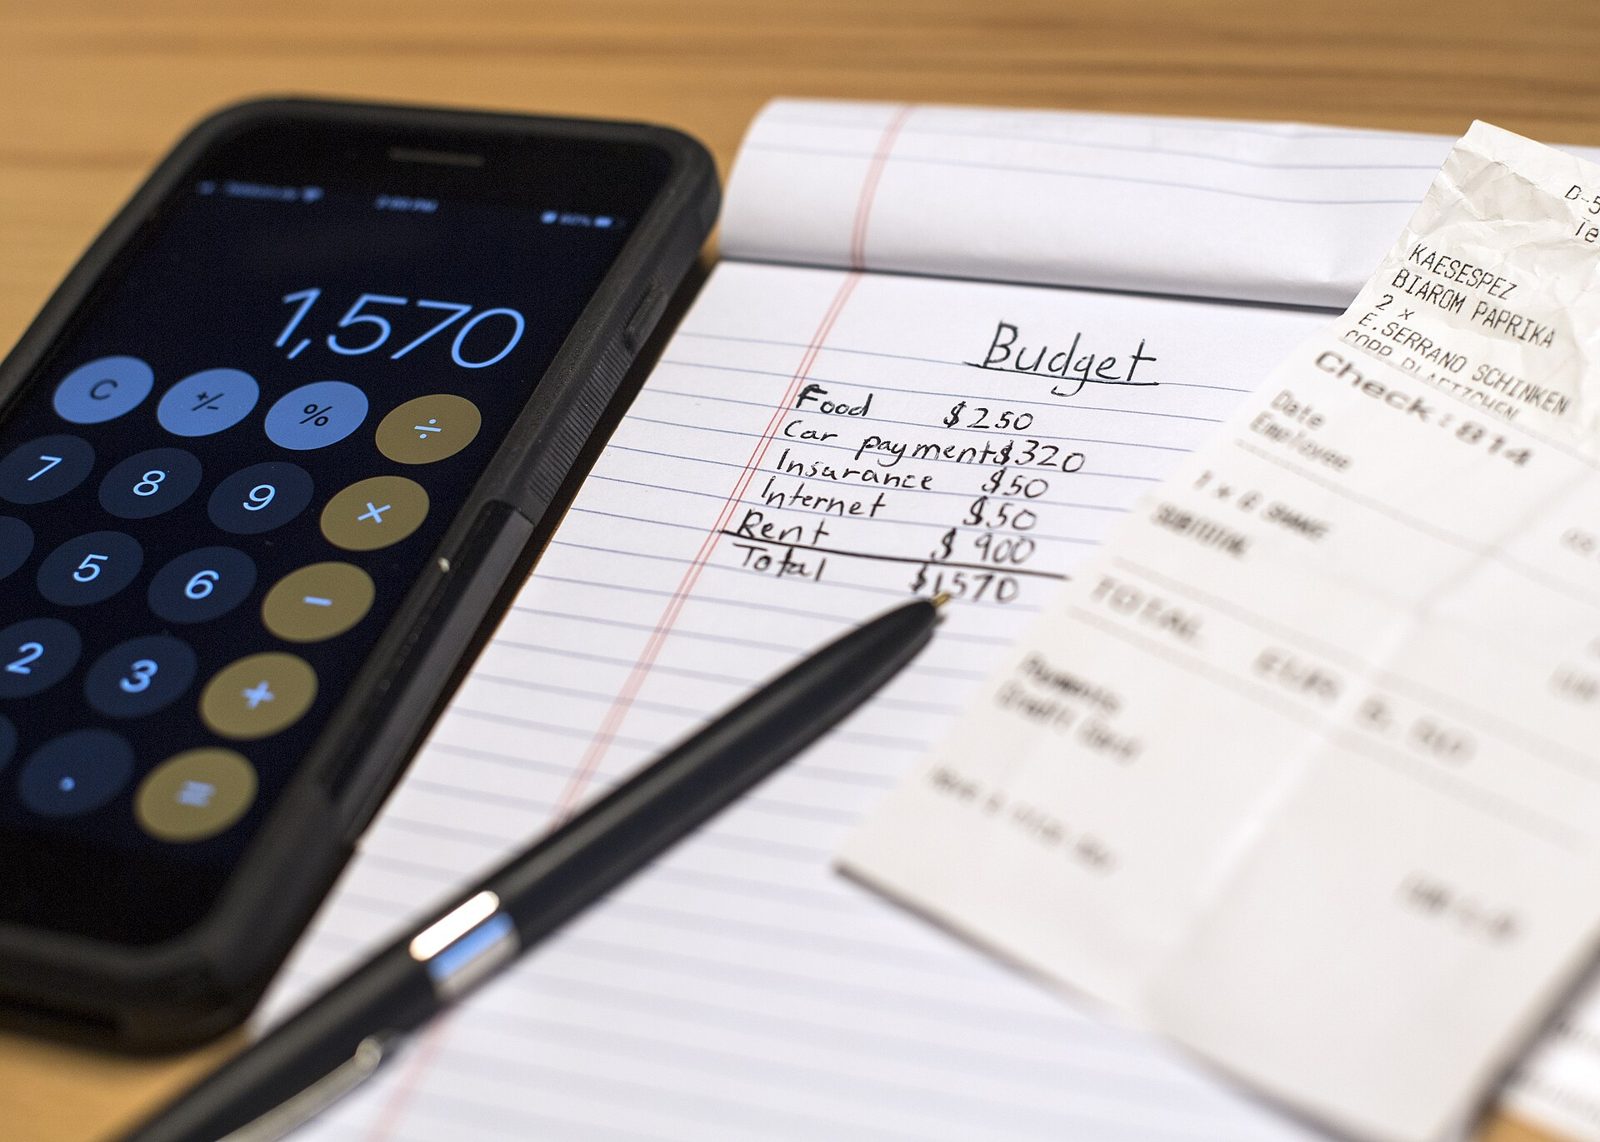
Grab a sheet of paper or open a spreadsheet and list your take-home pay, then your fixed bills with their due dates, the amount you want to save and invest, and what remains for flexible spending. This map becomes your blueprint for every automation that follows.
Step one: retirement contributions
If your employer offers a retirement plan, set up payroll contributions first. This money leaves your paycheck before it reaches your bank account, which makes it the most effortless form of saving. Contribute at least enough to receive any employer match, since that match is part of your compensation. Many plans also offer an automatic increase feature that raises your contribution by a small percentage each year.
Step two: automatic savings
Next, schedule an automatic transfer from checking to savings for the day after payday. Choosing the day after ensures your paycheck has cleared. If you’re building an emergency fund, a high-yield savings account at a federally insured bank keeps that money separate and earning interest. Some employers also let you split direct deposit so part of each paycheck goes straight into savings.
Step three: fixed bills
Set up autopay for bills that are the same or similar every month, such as rent or mortgage, utilities, insurance premiums, phone and internet, and loan payments. Many companies let you choose your due date, so it can help to align due dates shortly after payday. Some lenders and service providers offer a small discount for enrolling in autopay.
Step four: credit cards
For credit cards, set autopay for at least the minimum payment so you never miss a due date, which protects your credit score from late payments. Ideally, set it to pay the full statement balance. Paying in full each month means you avoid interest entirely.
Step five: investing
Beyond your workplace plan, schedule regular contributions to an IRA or taxable brokerage account. Investing a fixed amount on a regular schedule, sometimes called dollar-cost averaging, builds wealth steadily and removes the temptation to guess when the market is about to move.
Step six: spending money
Whatever is left in checking after all of these automations is your spending money for groceries, gas, entertainment and everything else. Some people go a step further and move a fixed weekly spending amount into a separate account or onto a debit card so they always know exactly what is available.
Keep a buffer
Automatic payments can occasionally overlap with a paycheck that arrives late or a bill that is larger than usual. Keep a cushion in checking, perhaps a few hundred dollars or one week of expenses, so a timing shift doesn’t overdraw your account. Many banks also offer low-balance alerts, which give you an early warning.
Stay in charge
Automation should save you time, not take you out of the loop. Look at your accounts once a week to confirm that payments went through and nothing looks unusual. Review bills monthly for errors, unexpected price increases or charges you don’t recognize. Every few months, go through your subscriptions and cancel anything you no longer use, because autopay makes it easy to keep paying for things you forgot about.
Adjust as life changes
Your automations should evolve with your life. When you get a raise, increase your savings and investment transfers before your spending rises to match. When you pay off a debt, redirect that payment toward a new goal. If your income drops or a new bill appears, update your transfers so the system still works.
Set a reminder to review your setup at least once a year. A quick check keeps your automations aligned with your current goals and ensures your money keeps flowing exactly where you want it.
Content on The Evergreen Edit is for educational and informational purposes only and is not individualized financial, investment, tax or legal advice. Learn more.
This article is for educational purposes only and isn't personalized financial, tax or legal advice. Consider talking with a qualified professional about your situation.

Kiara Miller — Founder & Editor
Kiara Miller is the founder and editor of The Evergreen Edit. He has been doing independent finance research for two decades and reviews every article before it's published.
More about Kiara →Get smarter about your money.
Join readers who get The Sunday Edit every week.